Singapore Market Entry
What to establish before you register a company here
Structure, licensing and channel questions worth answering before incorporation rather than after it.
Jump to 10 sections
Registering a company is often treated as the starting point for entering Singapore. It feels concrete. There is a company name, a registration number and an entity that can begin opening accounts, signing agreements and hiring people.
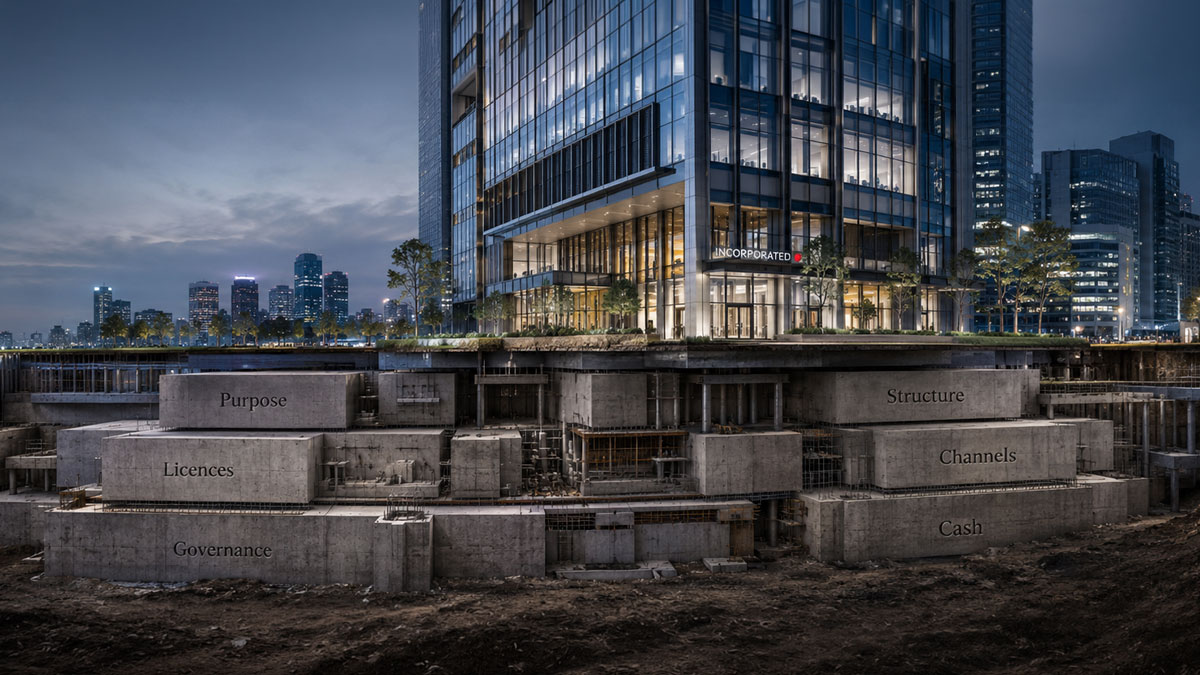
However, incorporation should not be the first major market-entry decision.
Before registering, a business should understand what its Singapore operation will actually do, which regulatory requirements apply and how it intends to reach customers. Without that clarity, the company may end up with the wrong structure, unsuitable licences, unnecessary costs or a sales model that does not work as expected.
The registration process creates a legal entity. It does not create a viable operating model.
注册公司常被视为进入新加坡市场的起点。这件事很具体:公司有了名称、注册号码和法人实体,便可以着手开户、签订协议和聘用员工。
然而,公司注册不应成为市场进入过程中的第一个重大决定。
注册之前,企业应先了解新加坡业务实际要做什么、适用哪些监管要求,以及准备如何接触客户。如果这些问题尚未明确,公司可能选错架构、申请不合适的牌照、承担不必要的成本,或采用无法达到预期的销售模式。
注册程序建立的是一个法律实体,而不是一个可行的运营模式。
01
Begin with the role of the Singapore operation
The first question is not, “How quickly can we incorporate?”
It is, “Why do we need a Singapore entity?”
Different businesses establish themselves in Singapore for very different reasons. One company may need a regional sales office. Another may want to hire employees, import products, hold inventory or contract directly with local customers. A third may only want to research the market and build relationships before making a larger commitment.
These situations require different structures and levels of investment.
Before incorporation, management should agree on several practical points:
What products or services will be offered in Singapore?
Will the Singapore operation generate revenue?
Which entity will sign customer and supplier contracts?
Which entity will issue invoices and collect payments?
Will the company employ people locally?
Will it import, export or store physical goods?
Will it own intellectual property or other assets?
Will it serve Singapore only, or support a wider Southeast Asian operation?
Which decisions can be made locally?
Which decisions must remain with the overseas headquarters?
These questions may sound operational, but they shape almost every later decision. They affect the legal structure, banking arrangements, staffing plan, tax position, licence requirements and choice of sales channel.
For example, a company that only wants to conduct market research may not need the same structure as one that intends to sign multi-year customer contracts and employ a full local team. Likewise, a business selling software directly from overseas may face different considerations from a company importing food, medical devices or consumer products.
A clear operating model should therefore come before the incorporation documents.
第一个问题不是“我们最快多久可以注册公司?”,而是“我们为什么需要一个新加坡实体?”
不同企业在新加坡设立业务的原因差异很大。有的需要区域销售办公室;有的希望在本地招聘、进口产品、持有库存或直接与客户签约;还有的只想先研究市场、建立关系,再决定是否作出更大投入。
这些情形所需的架构和投资程度并不相同。注册之前,管理层应就以下实际问题达成一致:
将在新加坡提供哪些产品或服务?
新加坡业务是否会产生收入?
由哪个实体与客户及供应商签约?
由哪个实体开具发票并收取款项?
是否会在本地聘用员工?
是否会进口、出口或储存实物商品?
是否会持有知识产权或其他资产?
业务只服务新加坡,还是支持更广泛的东南亚市场?
哪些决定可以在本地作出?
哪些决定必须由海外总部保留?
这些问题看似属于运营层面,却会影响之后几乎所有决定,包括法律架构、银行安排、人员配置、税务状况、牌照要求和销售渠道。
例如,只想进行市场调研的公司,不一定需要与计划签订多年客户合约并建立完整本地团队的公司采用相同架构。直接从海外销售软件的企业,与进口食品、医疗器械或消费品的企业,面对的考虑事项也不一样。
因此,应先建立清晰的运营模式,再准备公司注册文件。
02
Choose the structure that reflects the commercial plan
Foreign businesses have several ways to establish a presence in Singapore. According to the Accounting and Corporate Regulatory Authority, the principal options include a representative office, a local company or subsidiary, a foreign company branch and re-domiciliation. Each option has different implications for legal status, liability, income-generating activities and compliance.
Representative office
A representative office can be useful when a company wants to study the market before committing to full commercial operations.
It is a temporary arrangement and is not a separate legal entity from the overseas parent. It may be used for activities such as market research and relationship building, but it cannot earn income. The parent company remains responsible for its activities.
This option may suit businesses that are still testing demand. It is less suitable when the business is ready to invoice customers, sign commercial contracts or conduct revenue-generating activities.
Local company or subsidiary
A Singapore subsidiary is a separate legal entity owned by its shareholders, which may include an overseas parent company. It can conduct full commercial operations, earn income, hold assets and enter contracts in its own name.
A local company also provides a clearer separation between the Singapore business and the overseas parent. ACRA states that a company is a separate legal entity and that shareholders generally have limited liability for its debts and losses.
This structure is often considered when a business intends to build a lasting operation, employ staff, work with local partners or assume contractual responsibilities in Singapore.
That does not automatically make it the correct choice. The parent company should still decide how much capital to commit, what authority the local board will have, how profits may be distributed and which risks should sit within the Singapore entity.
Foreign company branch
A branch is an extension of the overseas company rather than a separate legal entity. It may earn income and operate commercially in Singapore, but the parent company remains fully responsible for its liabilities.
A branch may be appropriate when customers, regulators or commercial partners expect to contract with the established overseas company itself. However, the absence of legal separation should be considered carefully, particularly where the Singapore operation could take on significant contractual, employment or product-related risk.
Re-domiciliation
Re-domiciliation allows an eligible foreign company to transfer its legal home to Singapore and become a Singapore company. It is a much broader decision than opening a local office because it changes the company’s place of registration rather than simply adding a Singapore operation.
This option is generally relevant when a company is considering moving its corporate base, rather than establishing an additional market presence.
外国企业可通过多种方式在新加坡建立业务。根据新加坡会计与企业管理局(ACRA)的资料,主要选项包括代表处、本地公司或子公司、外国公司分公司,以及迁册。每种选项在法律地位、责任、创收活动和合规方面都有不同影响。
代表处
如果企业希望在全面开展商业运营前先研究市场,代表处可能是合适的临时安排。代表处并非独立于海外母公司的法律实体,可用于市场研究和建立关系等活动,但不能赚取收入,其活动仍由母公司负责。
这种方式较适合仍在测试需求的企业;如果已经准备向客户开票、签订商业合约或开展创收活动,则通常不合适。
本地公司或子公司
新加坡子公司是由股东拥有的独立法律实体,股东可以包括海外母公司。它能够开展完整商业运营、赚取收入、持有资产并以自身名义签订合约。
本地公司也能更清楚地区分新加坡业务与海外母公司。ACRA 指出,公司是独立法律实体,股东对公司的债务与亏损通常承担有限责任。
当企业准备建立长期业务、聘用员工、与本地伙伴合作或在新加坡承担合约责任时,通常会考虑这一架构。但这不代表它必然是正确选择。母公司仍须决定投入多少资本、本地董事会拥有多大权限、利润如何分配,以及哪些风险应由新加坡实体承担。
外国公司分公司
分公司是海外公司的延伸,而非独立法律实体。它可以在新加坡赚取收入和开展商业运营,但其责任由母公司完全承担。
如果客户、监管机构或商业伙伴希望直接与既有海外公司签约,分公司可能合适。不过,企业应审慎考虑缺乏法律隔离所带来的影响,尤其当新加坡业务可能承担重大的合约、雇佣或产品责任时。
迁册
符合资格的外国公司可通过迁册把法定注册地转移至新加坡,成为新加坡公司。此举改变的是公司的注册归属,范围远大于增设一个本地办事处,通常只适用于考虑迁移企业总部注册地的公司,而不是单纯增加一个市场据点。
03
Treat governance as a real responsibility
A company should not appoint directors simply to complete the registration process.
Singapore companies must have at least one director who meets the applicable local residency requirements. Directors are responsible for the company’s strategy, records, filings and compliance, and ACRA makes clear that there is no concept of an inactive or “sleeping” director who is free from responsibility.
A company secretary must also be appointed within six months of incorporation. The secretary helps maintain company information and registers, organise meetings and manage filing deadlines.
Before registering, the business should establish:
Who will sit on the board?
Who will have authority to sign contracts?
Who will approve expenditure?
Which matters require approval from the parent company?
How will conflicts between local management and headquarters be resolved?
Who will be responsible for regulatory and corporate filings?
Does the proposed director understand the legal responsibilities of the role?
These questions are particularly important when a third-party nominee director is being considered. The appointment may help satisfy a residency requirement, but it does not remove the need for genuine oversight and clear governance.
Foreign businesses must also engage a registered corporate service provider to complete their Singapore registration. Foreign founders who plan to relocate and run the business locally must separately consider the relevant work-pass requirements.
企业不应只是为了完成注册手续而任命董事。
新加坡公司必须至少有一名符合相关本地居住要求的董事。董事须对公司的战略、记录、申报与合规负责;ACRA 明确指出,不存在无需承担责任的“休眠”董事。
公司还须在注册成立后六个月内委任公司秘书。公司秘书协助维护公司资料与登记册、安排会议并管理申报期限。
注册之前,企业应明确:
谁将进入董事会?
谁有权签订合约和批准支出?
哪些事项需要母公司批准?
本地管理层与总部发生分歧时如何处理?
谁负责监管与公司申报?
拟任董事是否理解该职位的法律责任?
考虑委任第三方名义董事时,这些问题尤其重要。该安排可能有助于满足居住要求,却不能取代实质监督和清晰治理。
外国企业还须通过注册企业服务提供商办理新加坡公司注册。计划迁居新加坡并亲自经营业务的外国创办人,也必须另行考虑适用的工作准证要求。
04
Map the licences before making commitments
One of the most expensive market-entry mistakes is to assume that incorporation gives the company permission to conduct every activity listed in its business plan.
It does not.
Licensing may depend on the precise activity, product, customer group, premises, ownership arrangement and qualifications of the people involved. Requirements can apply to areas such as financial services, payments, healthcare, education, food, telecommunications, travel, employment services and the importation of controlled goods.
The business should therefore describe its full activity chain before registering.
It is not enough to say, “We are a technology company.” The company should identify what the technology does, who uses it, whether it handles payments, whether it provides regulated advice, whether it stores personal information and whether it connects customers with other service providers.
Similarly, “We sell consumer products” does not explain who imports the goods, whether they are regulated, where they will be stored or who is responsible for product labelling and customer returns.
When reserving a business name, the applicant must select Singapore Standard Industrial Classification codes for its primary and, where relevant, secondary activities.
Those activity codes matter. Certain business names or activities may be referred to another government agency for approval. ACRA states that this referral process may add up to 15 working days to the name application. It also warns that approval of a name or activity by ACRA does not necessarily mean that the business has received the separate sector licence it needs.
Businesses can use GoBusiness and its licence e-Advisers to identify licences and permits that may apply to particular activities.
Before incorporation, prepare a simple licensing map covering:
The activity being conducted
The responsible government authority
The licence, permit or approval required
The eligibility criteria
Any local personnel or qualification requirements
Any premises or inspection requirements
The expected application timeline
Whether operations may begin while approval is pending
The cost of applying and maintaining the licence
The consequences if the application is refused
This exercise may affect the proposed company name, business activity codes, staffing plan, premises and ownership structure.
It is better to discover those constraints before signing a lease or hiring a local team.
代价最高的市场进入错误之一,是误以为完成公司注册后,企业便获准开展商业计划中的所有活动。事实并非如此。
牌照要求可能取决于具体活动、产品、客户群、场所、所有权安排,以及相关人员的资格。金融服务、支付、医疗、教育、食品、电信、旅游、就业服务和受管制商品进口等领域都可能适用专门要求。
因此,企业应在注册前完整描述业务活动链。仅仅说“我们是一家科技公司”并不足够;还应说明技术的用途、使用者、是否处理付款、是否提供受监管建议、是否储存个人资料,以及是否连接客户与其他服务商。
同样,“我们销售消费品”并未交代由谁进口、产品是否受监管、存放在哪里,或由谁负责标签与客户退货。
申请保留公司名称时,申请人必须为主要业务和适用的次要业务选择新加坡标准产业分类(SSIC)代码。这些代码会产生实际影响:部分名称或活动可能转交其他政府机构审批。ACRA 指出,这类转介可能令名称申请增加多达十五个工作日;ACRA 对名称或活动的批准,也不等于企业已取得所需的行业牌照。
企业可使用 GoBusiness 及其牌照电子顾问,识别特定活动可能涉及的牌照和许可证。
注册前应制作一份简单的牌照清单,涵盖:
拟开展的活动;
主管政府机构;
所需牌照、许可证或批准;
资格标准;
本地人员或专业资格要求;
场所或检查要求;
预计申请时间;
等待批准期间能否开始运营;
申请与维持牌照的成本;
申请被拒时的后果。
这项工作可能改变拟用公司名称、业务活动代码、人员计划、场所和所有权架构。最好在签订租约或招聘本地团队之前发现这些限制。
05
Decide how customers will be reached
A legal entity is only useful if it supports a workable route to market.
Before registering, a company should decide whether it will sell directly, appoint a distributor or agent, work through resellers, use an online marketplace or combine several channels.
Each approach changes the role of the Singapore entity.
Direct sales
Selling directly gives the company greater control over pricing, customer relationships, brand positioning and service quality. The Singapore company may sign contracts, issue invoices and collect payments itself.
That control comes with additional responsibility. The company may need local salespeople, customer support, billing systems, marketing capability and a process for handling complaints, warranties and unpaid invoices.
Direct sales can work well when the product is complex, the customer relationship is important or the company needs close control over how the offering is presented.
Distributor or reseller
A distributor can provide local relationships, sales coverage and operational knowledge without requiring the overseas company to build a large team immediately.
However, the arrangement should not be treated as a simple outsourcing decision.
The business must decide:
Who sets the final customer price?
Who owns the customer relationship?
Who holds inventory?
Who pays import duties and GST?
Who provides technical support?
Who handles returns and warranty claims?
Can the distributor appoint sub-distributors?
Will the agreement be exclusive?
What sales targets must be achieved?
What happens to customers and stock when the agreement ends?
A distributor may provide faster access to the market, but the company may have less visibility over customers and less control over how the brand is represented.
Agent or referral partner
An agent may introduce or negotiate with customers while the overseas or Singapore company remains the contracting party.
This can be suitable for businesses that want local business development support without transferring the full customer relationship to a distributor. The commission structure, authority to negotiate, use of the company’s name and responsibility for regulatory statements should be documented clearly.
E-commerce and marketplaces
Online channels can help a company test demand without immediately building a physical sales network. However, they do not remove the need to answer legal and tax questions.
The company must identify the seller of record, the entity receiving payment, the party responsible for delivery and returns, and the party shown to the customer on invoices and contractual terms.
Overseas suppliers may also have Singapore GST obligations even without a locally incorporated company. Under the overseas vendor registration regime, an overseas business may be required to register where its annual global turnover exceeds S$1 million and its annual business-to-consumer supplies of remote services or low-value goods to Singapore exceed S$100,000.
This is an important reminder that incorporating locally and having tax obligations locally are related questions, but they are not always the same question.
一个法律实体只有在支持可行的市场渠道时才有意义。注册之前,公司应决定直接销售、委任分销商或代理、通过经销商或线上平台销售,还是结合多种渠道。不同选择会改变新加坡实体的角色。
直接销售
直接销售让公司更能控制定价、客户关系、品牌定位与服务质量。新加坡公司可以自行签约、开票并收款,但同时也要承担更多责任,可能需要本地销售人员、客户支持、计费系统、营销能力,以及处理投诉、保修和欠款的流程。
产品较复杂、客户关系重要,或公司必须严格控制产品呈现方式时,直接销售通常更合适。
分销商或经销商
分销商能提供本地关系、销售覆盖和运营知识,让海外公司无须立即建立庞大团队。但这项安排不能被视为简单外包。企业须明确:
谁决定最终客户价格并拥有客户关系?
谁持有库存、支付进口关税和消费税(GST)?
谁提供技术支持、处理退货和保修索赔?
分销商能否委任次级分销商,协议是否独家?
必须达到哪些销售目标?
协议结束后,客户与库存如何处理?
分销商可能加快进入市场,但公司也可能因此较难掌握客户情况,并减少对品牌呈现的控制。
代理或转介伙伴
代理可以介绍客户或参与谈判,而海外公司或新加坡公司仍作为签约方。这种模式适合希望获得本地业务开发支持,却不打算把完整客户关系交给分销商的企业。佣金架构、谈判权限、公司名称的使用,以及监管陈述责任都应清楚写入文件。
电子商务与线上平台
线上渠道有助于企业在尚未建立实体销售网络时测试需求,但不会消除法律和税务问题。公司仍须确定记录上的卖方、收款实体、负责交付与退货的一方,以及发票和客户条款所显示的主体。
即使未在新加坡注册公司,海外供应商也可能承担新加坡 GST 义务。根据海外供应商注册制度,如果海外企业的全球年营业额超过一百万新元,而且每年向新加坡消费者供应的远程服务或低价值商品超过十万新元,便可能需要注册。
这说明在本地注册公司与承担本地税务义务彼此相关,却不一定是同一个问题。
06
Establish the import and supply-chain model
Businesses dealing in physical goods should determine their customs model before the first shipment leaves the supplier.
To import goods into Singapore, an entity generally needs a Unique Entity Number, an activated Customs Account and a Customs Import Permit submitted through TradeNet. The importer may appoint a declaring agent to submit permits or register to make its own declarations.
Before incorporation, the business should decide:
Who will be the importer of record?
Will the Singapore entity purchase and own the goods?
Will a distributor import the products instead?
Who will appoint the freight forwarder and declaring agent?
Are the products controlled or subject to additional approvals?
Where will the goods be stored?
Who carries the risk if stock is damaged or unsold?
Who is responsible for customs declarations and supporting records?
Will products be sold only in Singapore or re-exported elsewhere?
How will import GST affect cash flow?
These decisions influence contracts, prices, margins and working-capital requirements.
For example, allowing a distributor to import the goods may simplify the overseas company’s operations, but it also gives the distributor greater control over stock and supply. Having the Singapore entity import directly provides more control, but requires the company to manage permits, logistics, inventory and tax.
Neither approach is automatically better. The correct model depends on the company’s commercial priorities and internal capability.
经营实物商品的企业,应在第一批货物离开供应商之前确定海关模式。一般而言,进口货物到新加坡需要统一机构识别号码(UEN)、已启用的海关账户,以及通过 TradeNet 提交的进口许可证。进口商可委任申报代理办理许可证,也可注册后自行申报。
注册之前,企业应决定:
谁是记录上的进口商?
新加坡实体是否购买并拥有货物,还是由分销商进口?
谁委任货运代理与申报代理?
产品是否受管制或需要额外批准?
货物存放在哪里,损坏或滞销风险由谁承担?
谁负责海关申报与支持文件?
产品只在新加坡销售,还是会再出口?
进口 GST 将如何影响现金流?
这些决定会影响合约、价格、利润率和营运资金。由分销商进口可能简化海外公司的运营,却会让分销商更能控制库存与供应;由新加坡实体直接进口可增加控制,但公司须自行管理许可证、物流、库存和税务。
两种方式没有绝对优劣,正确模式取决于公司的商业重点与内部能力。
07
Model tax and cash flow before revenue arrives
Tax planning should follow the real transaction flow.
The business should map which entity buys the product, which entity sells it, where services are performed, where invoices are issued and how money moves between the Singapore operation and overseas related companies.
GST should be considered early. Compulsory registration generally applies when taxable turnover exceeds S$1 million under the applicable retrospective or prospective tests. Where a business can reasonably expect taxable turnover to exceed S$1 million in the next 12 months, it must generally apply within 30 days of the relevant forecast.
Even where registration is not compulsory, the company may need to assess whether voluntary registration is commercially sensible. That decision can affect pricing, invoicing, import costs, accounting processes and relationships with customers.
The company should also prepare a realistic cash-flow model covering:
Incorporation and professional fees
Licence application and renewal costs
Salaries and employee-related costs
Office, warehouse or co-working expenses
Deposits and fit-out costs
Marketing and channel-partner commissions
Inventory and shipping
Import GST and duties
Insurance
Accounting and annual compliance
Technology systems and data protection
A contingency for delays in licensing or customer acquisition
A company may be easy to establish on paper but expensive to operate well. The initial budget should reflect the cost of reaching customers and meeting obligations, not merely the incorporation fee.
税务规划应根据真实交易流程进行。企业应梳理由哪个实体采购与销售产品、服务在哪里履行、发票从哪里发出,以及资金如何在新加坡业务与海外关联公司之间流动。
GST 应及早纳入考虑。当应税营业额在适用的追溯或前瞻测试下超过一百万新元时,一般须强制注册。如果企业有合理依据预期未来十二个月的应税营业额会超过一百万新元,通常须在相关预测出现后的三十天内申请。
即使无须强制注册,公司也应评估自愿注册是否符合商业利益,因为这会影响定价、开票、进口成本、会计流程和客户关系。
企业还应准备现实的现金流模型,包括:
注册与专业服务费用;
牌照申请和续期费用;
薪资及员工相关成本;
办公室、仓库或共享办公支出;
押金与装修成本;
营销与渠道伙伴佣金;
库存、运输、进口 GST 与关税;
保险、会计与年度合规;
技术系统与数据保护;
牌照或客户获取延误的应急预算。
公司在文件上可能很容易成立,但要把业务经营好却可能成本高昂。初始预算应反映接触客户和履行义务的真实成本,而不只是注册费。
08
Test the model before committing fully
A sensible market-entry process should challenge the assumptions behind the Singapore plan.
Speak to potential customers before deciding how large the local operation should be. Ask prospective distributors how they would position the product, what margin they require and which competing products they already represent. Confirm licence requirements directly with the relevant authority. Test whether customers expect a Singapore contracting entity or are comfortable purchasing from overseas.
The purpose is not to remove every uncertainty. That is rarely possible.
The purpose is to understand which assumptions are critical and which can be tested with limited cost.
A business may discover that customers require local invoicing, making a Singapore entity commercially valuable. It may discover that a distributor can manage imports and after-sales service, reducing the need for a large internal team. It may also discover that the intended activity requires a licence that changes the planned launch date.
Each of those findings should influence the incorporation decision.
合理的市场进入流程应主动挑战新加坡计划背后的假设。决定本地业务规模前,应先与潜在客户交谈;询问候选分销商会如何定位产品、需要多少利润率,以及目前代理哪些竞品;直接向相关主管机构确认牌照要求;并测试客户是否要求与新加坡实体签约,还是愿意向海外供应商采购。
目的不是消除所有不确定性——这通常不可能,而是理解哪些假设至关重要,以及哪些假设可以用有限成本验证。
企业可能发现客户需要本地开票,使新加坡实体具有明确商业价值;也可能发现分销商能够承担进口和售后服务,因而无须马上建立庞大内部团队;还可能发现某项牌照要求会改变预定上线日期。每项发现都应影响注册决定。
09
A pre-incorporation readiness check
Before registering, management should be able to answer yes to the following questions:
Is the purpose of the Singapore operation clearly defined?
Have the target customers and initial offering been identified?
Is it clear which entity will sign contracts and receive revenue?
Has the appropriate legal structure been assessed?
Have directors and governance responsibilities been agreed?
Have all relevant activities and business codes been identified?
Have potential licences and permits been checked?
Has the sales and distribution model been selected?
Is responsibility for importing, inventory and delivery clear?
Have GST and other tax implications been reviewed?
Is there a realistic staffing and work-pass plan?
Has the company modelled at least the first 12 months of operating cash flow?
Are there fallback options if a licence, hire or channel partnership is delayed?
Where several answers remain unclear, incorporation may be premature.
注册之前,管理层应能对以下问题作出肯定回答:
新加坡业务的目的是否已经清楚定义?
是否已经确定目标客户与首批产品或服务?
由哪个实体签约和收取收入是否明确?
是否评估过合适的法律架构?
是否已经商定董事与治理责任?
是否识别所有相关活动与业务代码?
是否查明可能适用的牌照与许可证?
是否选定销售和分销模式?
进口、库存与交付责任是否清晰?
是否审视 GST 与其他税务影响?
是否有现实的人员与工作准证计划?
是否模拟至少首十二个月的运营现金流?
牌照、招聘或渠道合作延误时,是否有替代方案?
如果其中多项仍不明确,注册公司可能为时过早。
10
Make incorporation the implementation step
Singapore offers a structured and well-established environment for setting up and operating a business. That can make the administrative process feel straightforward.
The strategic work is more demanding.
A company must still decide what role the Singapore entity will play, which risks it will carry, what permissions it requires and how it will reach customers profitably.
Answering these questions before incorporation does more than prevent compliance problems. It produces a clearer operating plan, a more realistic budget and a stronger basis for deciding whether a Singapore entity is needed at all.
Register when the company knows what it is building.
At that point, incorporation is no longer an experiment. It becomes the practical implementation of a considered market-entry strategy.
This article provides general information and does not constitute legal, tax or regulatory advice. Businesses should confirm their specific obligations with the relevant Singapore authorities and qualified professional advisers.
新加坡具备成熟、规范的企业设立与运营环境,因此行政程序看起来相对直接,但战略工作远为复杂。
企业仍须决定新加坡实体扮演什么角色、承担哪些风险、需要哪些许可,以及如何以可持续利润接触客户。
注册前回答这些问题,不仅能预防合规问题,也能形成更清晰的运营计划、更现实的预算,并为判断是否真的需要新加坡实体提供更坚实的依据。
当公司清楚知道自己要建立什么时再注册。到那时,公司注册不再是一次试验,而是经过审慎考虑的市场进入战略的实际执行。
本文仅提供一般信息,不构成法律、税务或监管建议。企业应向相关新加坡主管机构及具备资格的专业顾问确认自身的具体义务。
Written by
SVG Editorial
Notes written from live advisory, market-access and business-improvement work. Where an article draws on a client engagement, it is published without identifying details.
Related service
Market Access & Representation
Singapore–China market exploration, local representation and distribution
Discuss Market Access